Your Latte Habit Is a House Down Payment in Disguise
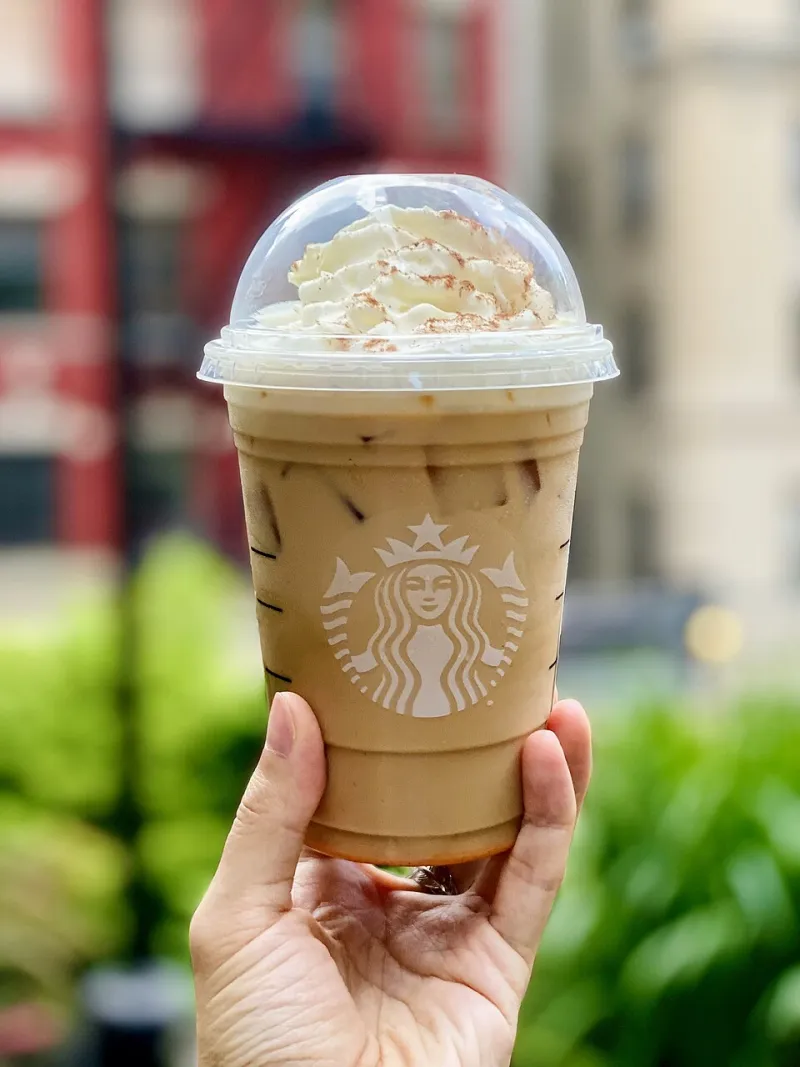
Photo: JimmyStardust, CC BY-SA 4.0, via Wikimedia Commons
Every financial guru has a latte story, and most of them are insufferable. But here's the thing nobody tells you: the actual math on a daily coffee shop habit is worse than the gurus claim. Not better. Worse. Because they usually just multiply the price by the days and stop there, missing the three costs that stack on top of each other like a triple shot of espresso.
Let's run the real numbers.
The Sticker Price: $22,000 and Change
A medium latte at a typical US coffee chain runs about $6 now, once you factor in tax and a tip on the card reader. Buy one every workday — 260 days a year — and you're spending roughly $1,560 annually. Over ten years? Around $15,600.
But most people don't just do workdays. Add weekend runs and the occasional afternoon pick-me-up, and you're closer to 320 purchases a year, or about $19,200 a decade. Round it up with price increases (coffee prices have climbed faster than inflation for years) and you're staring down $22,000.
That's not a latte problem. That's a used Honda Civic problem.
The Interest You Never Earned
Here's where it gets ugly. That money wasn't just spent — it was invested in nothing. Every dollar you hand across the counter is a dollar that didn't compound.
Drop that same $1,560 a year into an S&P 500 index fund instead, assuming a conservative 7% average annual return, and after ten years you'd have roughly $23,000. After twenty? Around $68,000. The coffee itself was $22,000. The missed growth is another $45,000 or so. Your habit didn't cost $6 a day — it cost closer to $90 a day by the time the decade closed.
The 401(k) Match You're Leaving on the Table
This is the part that stings the most. If your employer matches 401(k) contributions up to, say, 4% and you're not maxing it because money feels tight — but you're also spending $130 a week on espresso drinks — you're effectively paying a fee to skip free money.
A match is a guaranteed 100% return. No index fund in history can promise that. Redirecting even half your coffee budget into your 401(k) to capture a full match could mean thousands of extra dollars a year that your employer hands you for the crime of filling out a form.
The 80% Solution: Brew at Home, Keep the Buzz
Nobody's asking you to drink sad breakroom coffee. The goal is keeping 80% of the spending, not 100% of the sacrifice.
Here's the breakdown:
- Basic home setup: A decent burr grinder and pour-over or drip machine costs $60–$100 one time. Beans run $12–$15 a bag, which makes roughly 30 cups. Your per-cup cost drops to about 50 cents.
- Latte at home: Add an entry-level milk frother ($30) and whole milk, and your homemade latte costs about $1.10.
- The math: 300 homemade lattes a year at $1.10 is $330 versus $1,800+ at the shop. You keep roughly $1,470 annually — an 80%+ savings — and still drink actual lattes.
Treat the coffee shop as a Friday treat instead of a daily ritual and you get the social ritual, the barista art, the whole experience — for a fifth of the price.
The Any-Habit Calculator
Want to run this framework on energy drinks, vending machine snacks, or a daily gas station soda? Here's the formula:
- Daily cost × 320 = your realistic annual spend (320 accounts for how habits actually behave, not how you wish they did).
- Annual spend × 10 = your decade price tag, before growth.
- Plug the annual amount into a compound interest calculator at 7% for 10 years = what that habit really cost you in wealth.
- Check your 401(k) match. If you're not capturing it, your habit is doubly expensive.
- Find the 80% substitute. Almost every small daily vice has a home version that costs a fraction of the retail one.
Run it once. The results tend to be motivating in a way no budgeting app notification ever manages to be.
Your latte isn't the enemy. The unexamined autopay of it is. Look at the number, decide what it's worth to you, and keep whatever's left.